Issue#127, Volume#3

The Mind Of A Nobel Winner, A Heart Of Pure Gold
Inside Today’s Issue
Editor’s note: Today, Porter turns the Daily Journal over to his colleague, Distressed Investing analyst Marty Fridson. Marty spent years at leading firms like Salomon Brothers, Morgan Stanley, and Merrill Lynch. While doing innovative work in credit analysis and investment there, he became friends with the late Martin Leibowitz – the subject of today’s essay.
Here’s Marty…
There’s more to life than a yield curve…
Earlier this summer, I attended a memorial service for Martin Leibowitz, a giant of financial analysis whom I had the great privilege of getting to know when I worked at Salomon Brothers in the 1980s.
The event’s distinguished speakers explained how he revolutionized bond management. One opined that if Marty had published his work as an academic rather than a practitioner, he would have received a Nobel Prize in Economics. As it was, he published more articles in the prestigious Financial Analysts Journal than anyone else and won numerous awards for his contributions.
Even more impressive than the recitations of his extraordinary accomplishments was the praise of his character. On Wall Street, brilliance is rarely found in combination with humbleness, but Marty exemplified both qualities. People meeting him for the first time expected to be intimidated by his intellect, but he instead made them feel special by taking a sincere interest in them. One speaker recounted how, newly arrived from India and with little experience, he approached the legendary man fearing he’d be overawed by a barrage of technical talk far beyond his comprehension. But Marty most of all wanted to know what his name meant in Sanskrit.
Hearing these comments, as well as descriptions of Marty’s wonderful sense of humor and his devotion to his family, it occurred to me that he could have written another book just as successful as Inside The Yield Book (co-authored with Sidney Homer), which became the bible for newcomers to the bond business. If he’d distilled his approach to dealing with his fellow human beings into a volume along the lines of Dale Carnegie’s How To Win Friends And Influence People, it would have been a bestseller.
In the bond world, Marty transformed the way portfolio managers perceive their jobs. Before he came along, they basically had two options:
- Buy-and-Hold
- Try to gain an edge over a market benchmark, one bond swap at a time
That second option involved transactions such as switching to a longer-maturity bond, which will experience a bigger gain if interest rates fall – and being right about which way interest rates are headed. After Marty’s work became known, portfolio managers and chief investment officers saw the task as designing the most efficient portfolio to achieve the institution’s long-range objectives, for example, satisfying pension obligations or funding an insurance company’s liabilities.
Marty’s extraordinary influence over bond managers’ practices resulted from two factors. One was his application of highly sophisticated mathematics. The other was his ability to explain the practical implications of his findings in terms accessible to people lacking a PhD. A sad truth is that many supersmart financial researchers know how to communicate only with other quants and consequently have far less impact than they might.
Another key reason that Martin Leibowitz became the obvious choice to be the very first inductee to the Fixed Income Analysts Society Hall of Fame was that he sincerely and passionately wanted to get to the right answer.
That might seem the obvious way to go about things, but it’s not how all Wall Street research is done. Too much of it is conducted with an eye toward confirming a predetermined conclusion. Evidence that fails to support the desired message – “You should buy this!” – is excluded from the analysis. Marty had a master’s degree in physics and applied that discipline’s rigorous scientific method as fully as possible to finance.
As an investor, you need to be on your guard against research that doesn’t measure up to Marty Leibowitz’s standards. Make sure the findings are not just assertions, but instead are backed up by logically sound arguments.
When Marty started making his logically sound arguments at Salmon Brothers in the 1970s, his conclusions weren’t universally welcomed on the trading desks. He showed that the valuation methods then being used there were mathematically incorrect. The traders’ reaction was, “I’ve been consistently profitable. Where does this rocket scientist get off telling me I’ve been doing it wrong?”
Later on, though, they became more accepting of the brainy newcomer. The practice among traders was to agree to a transaction based on the yield of the bond they were buying or selling. To translate the yield into a price, such as 95.5, or $950 per $1,000 face amount, they’d go to the “yield book.” That was a thick volume containing rows of coupon rates and periods-to-maturity, matched up with prices.
But the coupon rates shown in the tables went up only as high as 6%. As rates rose above that level, the traders had to turn to another source. That was Marty, who had a computer terminal at his desk and knew how to get it to calculate prices based on the numbers they brought to him. The Wall Street Technology Revolution was underway and Marty Leibowitz was at the forefront!
Years later, I had the great fortune of getting to know Marty on a social level as a result of his involvement, along with his wife Sarah, in the Orpheus Chamber Orchestra. My wife, Elaine Sisman, is a musicologist specializing in Haydn, Mozart, and Beethoven.
At the memorial service, a chamber group consisting of orchestra members played some of Marty’s favorite pieces, ending with “Londonderry Air,” otherwise known as “Danny Boy.” That irresistible melody was a fitting tribute to a life very well lived.
Tell us what you think of today’s Journal: porterstansberrydirect@gmail.com
Good investing,
Martin Fridson
New York, New York
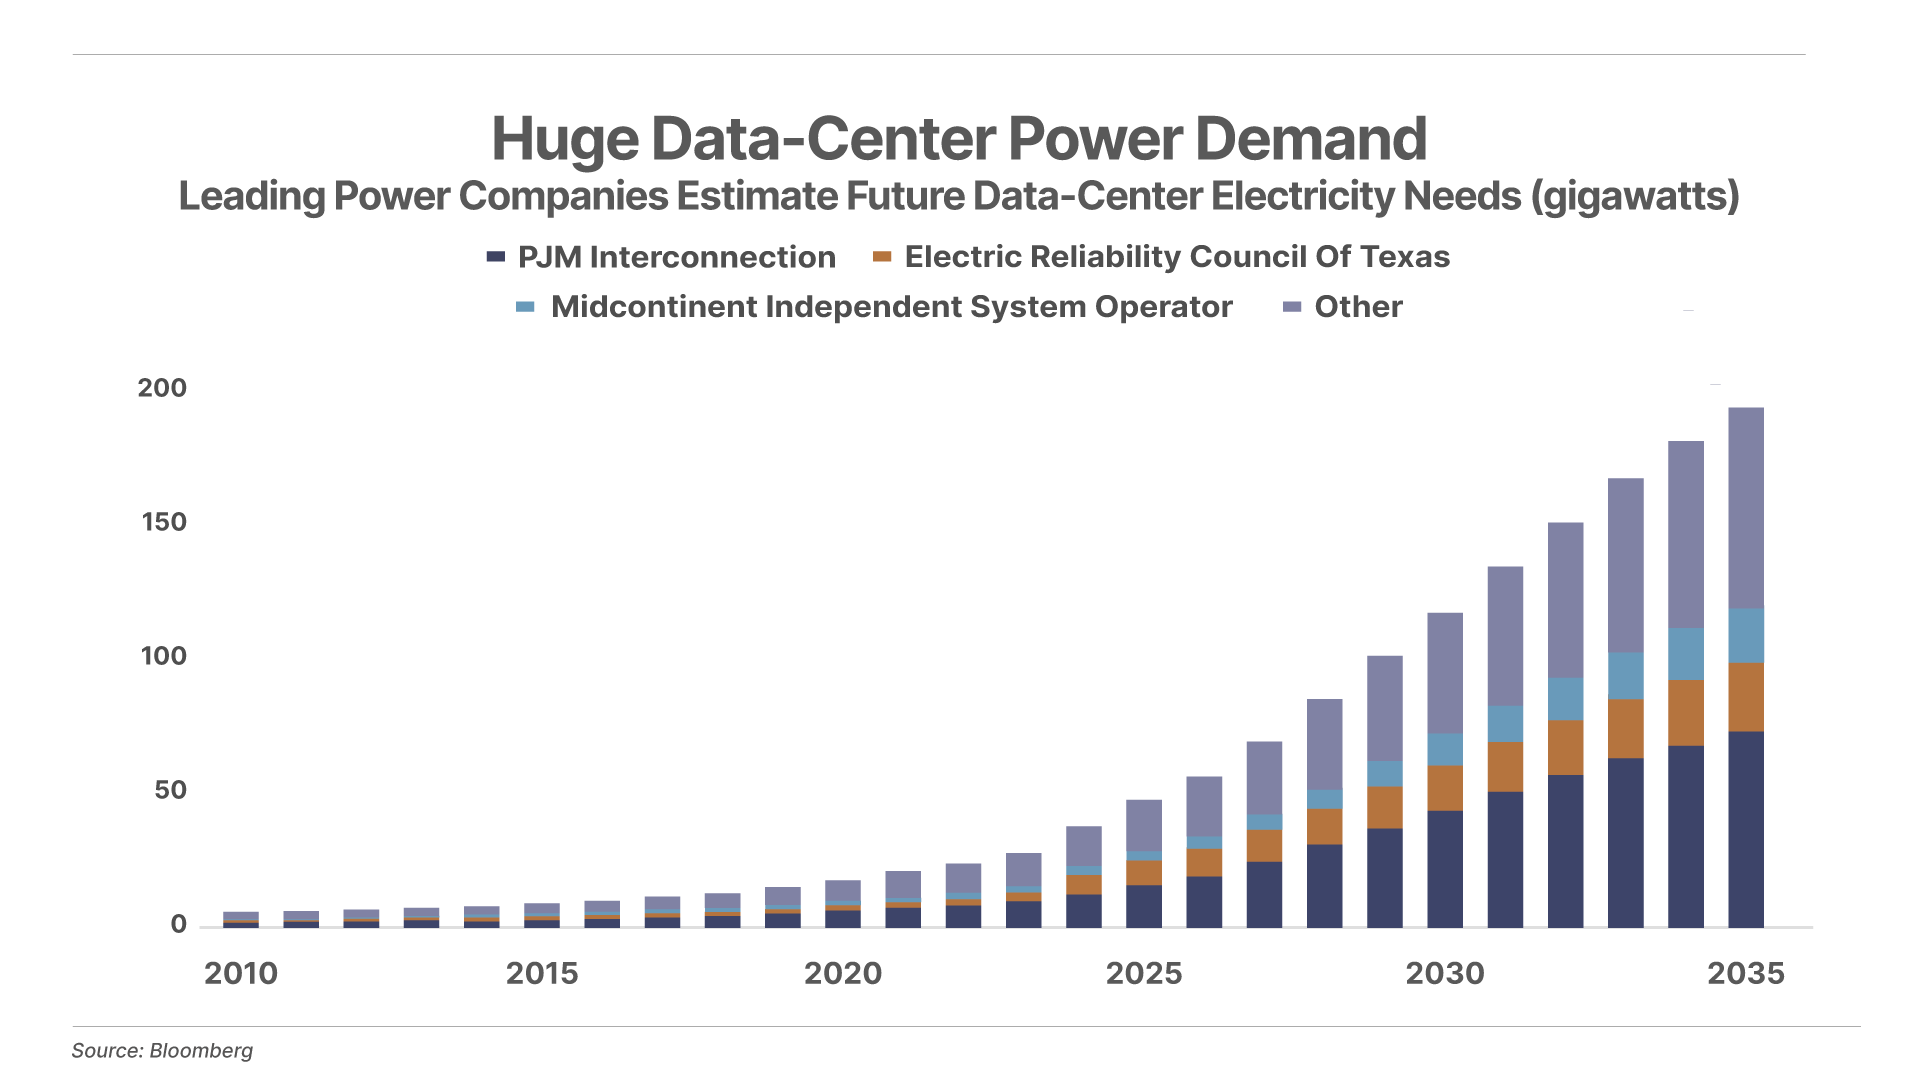
1. Data centers will devour one-fifth of the U.S. grid. BloombergNEF projects data-center power demand will climb 253% to a record 194 gigawatts by 2035. That would lift data centers’ share of national electricity consumption from 5.9% to 20% in 10 years. The strain will be highly regional, particularly for PJM Interconnection, home to Northern Virginia’s “Data Center Alley,” and Texas’s ERCOT market. Power generation is the next AI bottleneck: the U.S. isn’t building generation anywhere near fast enough to meet that curve.
2. Pain in the market’s most crowded trade. Chip stocks have been the hottest area of the market, with $46 billion in new money pouring into the sector in 2026 – more than the previous nine years combined. Now the trade is coming undone, with the semiconductor index down 20% in the last five weeks. Some of the highest-momentum stocks in the group, like memory chipmakers Sandisk (SNDK) and Micron Technology (MU), have dropped 50% from their highs.
3. Big employers are hiring again, defying AI fears. After a year of shunning new hires, companies like Alphabet (GOOG), government contractor Booz Allen Hamilton (BAH), and railroad giant CSX (CSX) told investors this month they need more people – to work alongside AI, despite fears that the new technology will replace workers. Weekly jobless claims fell to 187,000 in the week that ended July 18, the fewest since September 1969.
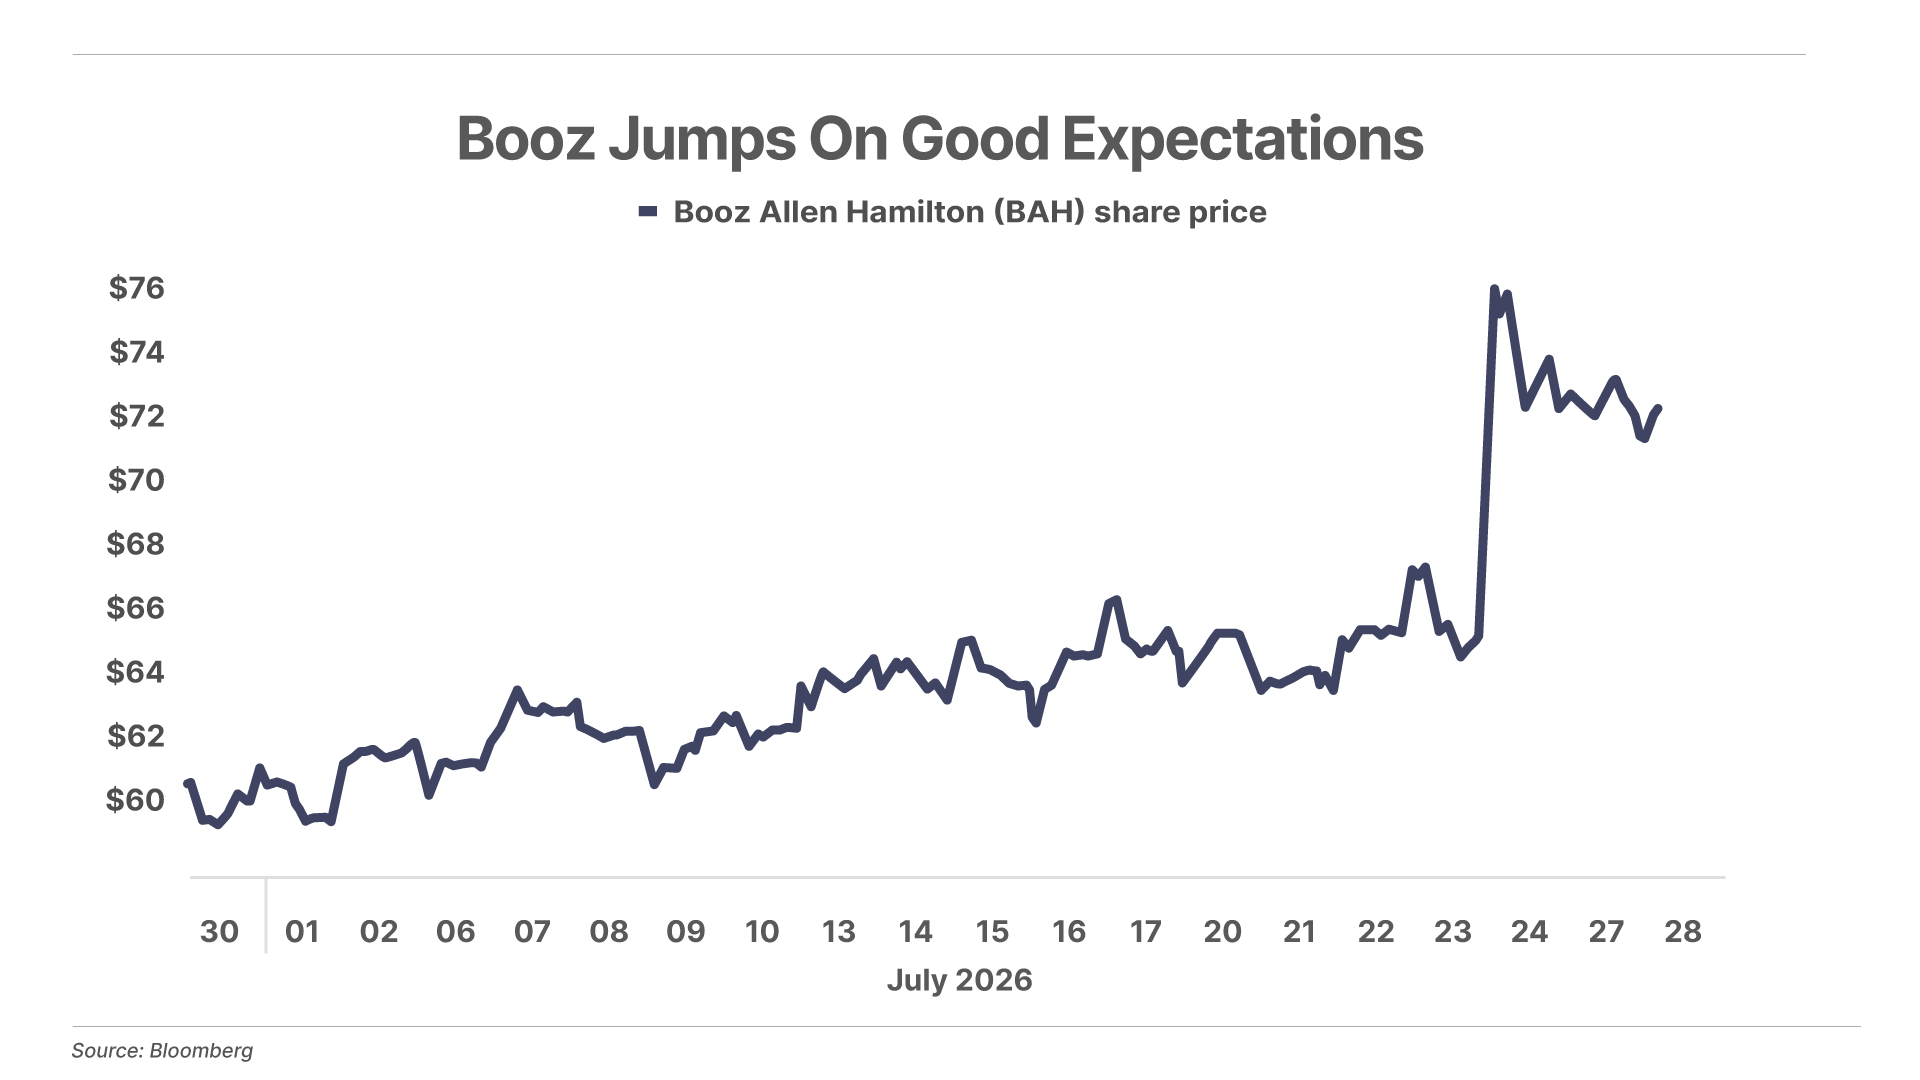
Shares of Complete Investor recommendation Booz Allen Hamilton (BAH) have jumped 16% over the past month, sparked by fiscal Q1 earnings, when a 1.5x book-to-bill ratio and strong full-year guidance signaled the federal procurement freeze may finally be thawing.
Today’s Poll… Will The Fed Cut Rates Tomorrow?
Tomorrow, the Federal Open Markets Committee (“FOMC”), led by Fed Chair Kevin Warsh, will vote on future interest rate policies. The market is pricing about a one-in-three chance of an interest rate hike. Why? June inflation was mild, but oil prices are up 20% and inflation is well above its 2% target at 3.5%.
“You Missed The Mark”
In yesterday’s Daily Journal, Porter presented his third in a series on great American brands that forgot what they really sell – it featured Ford Motor (F) and how it’s gone wrong.
Steve B. writes:
I believe your article on Ford misses the mark!
This year in January I crossed the 50-year mark working in and around the auto industry – 30 years with an original equipment manufacturer (“OEM”), eight years with a major supplier as a SVP / corporate officer, six years winning, designing, building, and opening my own BMW dealership, and the last six years advising automotive CEOs.
First, former Ford CEO Jim Hackett is easily the second-biggest sack of shit to hold the CEO title for a major OEM – the absolute biggest all-time sack of shit is General Motors CEO Mary Barra. Both are ignorant, political whores.
Both have destroyed their respective companies, destroyed the technological capability within their companies, and both have no idea what they are doing. I could write a book on this topic!
What you should be writing is do NOT invest one penny in either of these companies as both are over 50% non-competitive against the Chinese OEMs: BYD, Chery, Geely, Great Wall Motor, etc. The Chinese are coming and when they do, both of these companies are finished – more than likely both will be taken over by the Chinese.
I know this industry to the point in the last two weeks I’ve been asked to rejoin the corporate world as a CEO for one company, and as a COO for another company.
I’d be happy to discuss this subject with you, as you really need to warn your readers: Ford and GM are both headed for very tough days ahead! And the truly sad thing, their leadership is too arrogant and ignorant to understand just how uncompetitive they are, and how their lunch is going to be taken!
All the best
Porter Comment: Steve –
I’m not sure what article you read.
I said that Ford’s executives deserve to be shot. I’m not sure how I could have been more critical of them than that… maybe I should have said “find a rope.”
Sincerely, I cannot understand how you could have read my piece and come away thinking that I was recommending investing in Ford. I just explained how the management team took $16 billion and lit it on fire. So, no, I don’t think owning Ford is a good idea. And, by the way, GM is worse.
Regards,
Porter
P.S. You should see my Letters From The Chairman Of General Motors from 2007. I predicted the company’s 2008 bankruptcy by writing satirical letters from the chairman. That was the easiest short sell in history. Had to go to zero.
“You’re Being Unfair…”
Bob N. writes:
I think you may be a bit unfair to Ford. Certainly Ford has made all kinds of mistakes over the years, but I suspect the electrification wasn’t just a whim on their part. Remember, they’ve certainly been under enormous pressure from the government, which has been pushing for electrification of all sorts of things. Certainly under the Biden administration and it will almost certainly reimpose all the mandates under a future Democratic administration. And given that our society is largely 50/50, a future Democratic administration will certainly come. And of course businesses like Ford need a fairly long lead time to make major changes in designs and factories and whatnot, so it’s hard to make constant major shifts.
Porter Comment: The management of Ford has a legal fiduciary duty to its shareholders. If they couldn’t meet that duty because of political pressure, then they had a legal obligation to resign.
Sorry, but when you’re the steward of billions in other peoples’ capital and one of America’s greatest ever brands, you don’t get to make excuses.
Porter
“Some Idiots…”
Al G. writes:
It’s almost like Ford forgot who their typical truck buyer was when some idiots decided to make an electric F150! But then to stick to it for more than two years of losses was incredibly stupid. Who cares what the government is pushing – how can you give up so much control of your company? Shocking!
Regards
Rodger R. writes:
Damn straight, Porter!
David H. writes:
I have spent a lot of time in Alberta, Canada, where we expect the temperature to go -40 for a few days every winter. I still remember my dad using a propane heater to warm up the motor of his Mercedes so that it would start while I simply turned the key in my Ford station wagon.
On one trip, three cars tried to race me. They were all Pontiac Trans-Ams. I could beat them in second gear. They had been detuned for pollution controls so why the hell were they trying to race a real car?
Mark B. writes:
Your Ford analysis is spot on and frankly, I can’t see how ANYONE could fail to see a fix this simple.
The entire industry in total is awash in EV losses.
Keep telling it like it is!
Ross S. writes:
Your views on Ford are spot on! I’m no cowboy, nor do I need a truck for hauling my tools around since I was a general dentist when I was working. That said, I have owned a Ford truck for 40 of my 47 working years. They are just great trucks. I only had one over those 40 years that had any significant problems, and it was at only 27K miles. Ford took care of the problem with no out of pocket to me. That’s what I consider “customer care.” That’s why I keep buying Ford trucks, even though they are over $100,000 now. My last one – the SuperDuty F350 4X4 long bed Diesel King Ranch – is the most comfortable truck I’ve ever owned. It’ll tow your socks off your feet, which is why we bought it: for towing our travel trailer around the country.
Peter K. writes:
Here in Wyoming, Ford is the number-one selling truck. And Wyoming is full of cowboys and outdoor people. On our farm, the work truck is a Ford F350 Super Duty four-wheel-drive diesel. It’s 12 years old and still runs like new. The eight-foot bed works for moving stuff, and the crew cab comes in handy when more than two people are along for the ride. I expect to get another 12 years out of it at least. Take care of your truck, and it will take care of you.
Porter & Co. Market Snapshot
| Price | Yesterday’s Return | Year-to-Date Return | |
| S&P 500 Index | $7,413.18 | 0.02% | 9.0% |
| Gold per ounce | $4,076.26 | -0.37% | -6.7% |
| Bitcoin | $64,906 | 0.48% | -27.7% |
| Oil (West Texas Intermediate) per barrel | $82.61 | -4.08% | 41.8% |
| Berkshire Hathaway (BRK) | $745,840.00 | 0.11% | -1.2% |
| Porter’s Permanent Portfolio | – | 0.58% | 2.5% |
| The Better Than Berkshire Index | – | 0.48% | 9.1% |
| Total Return | Annual Return | ||
| Porter & Co’s Top Ranked* | 36.3% | 16.6% | |
| Yield | Yesterday’s Change | Change Year-to-Date |
|
| U.S Treasury 30-Year Yield | 5.14% | -2 bps | 29 bps |
| Prices as of 4:00 pm ET July 27, 2026 | bps = basis points (or 0.01%) | |||
| *A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio. | |||
Porter & Co. Top Positions
| Publication | Ticker | Description | Total Return |
| Tech Frontiers | QURE | uniQure | 237% |
| Complete Investor | BWXT | BWX Technologies | 210% |
| Tech Frontiers | NUVB | Nuvation Bio | 162% |
| Tech Frontiers | TGTX | TG Therapeutics | 157% |
| Tech Frontiers | ROIV | Roivant Sciences | 154% |
| Complete Investor | SKWD | Skyward Specialty Insurance | 149% |
| Complete Investor | PM | Philip Morris | 142% |
| Tech Frontiers | SGMT | Sagimet Biosciences | 138% |
| Complete Investor | BTC/USD | Bitcoin | 136% |
| Tech Frontiers | QURE | uniQure | 131% |
| Prices as of 4:00 pm ET July 27, 2026 | |||
Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.