Editor’s Note: On Tuesdays, we often turn the spotlight outside of Porter & Co. to bring you exclusive access to the research, the thinking, and the investment ideas of the analysts who Porter follows.
These are analysts Porter has known and followed for years, if not decades, whose ideas and insights have withstood the test of time, and who have helped Porter make better, more profitable investments.
If you’ve seen Porter’s recent interview with Garrett Goggin, you’ll already know why Porter says he is the best gold stock investor in the world (and his track record proves it beyond a shadow of a doubt).
You’ll also have heard Porter and Garrett explain why gold royalties companies are one the best ways to capitalize on gold’s coming bull run, potentially delivering far superior returns than bullion or coins.
In the guest Spotlight below (usually reserved for Garrett’s paying subscribers), he breaks down exactly why these companies are such phenomenal wealth-building vehicles.
Enjoy.
P.S. If you haven’t watched Porter and Garrett’s interview yet, do it today. It details why we’re on the cusp of the largest monetary re-alignment in decades, and how to best capitalize on it.
You can stream the full interview here.
*Disclaimer: Porter & Co. may receive compensation, referral fees, or other benefits if you purchase products or services mentioned in this email.
Randy Smallwood Should Be In Jail
From Garrett Goggin
Because he just stole $349 million from Hemlo Mining.
CEO of Wheaton Precious, Randy Smallwood just signed a stream agreement with Hemlo Mining on their newly acquired Hemlo mine from Barrick.
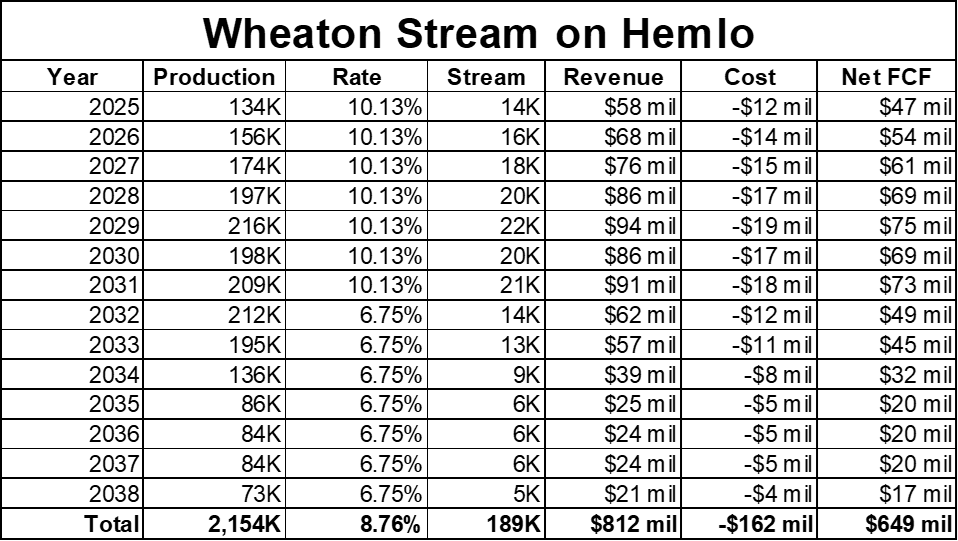
Wheaton is scheduled to receive a total of 189K gold ounces from Hemlo at 80% spot. That’s worth $649 mil at the current $4,300/oz gold price.
Wheaton only paid $300 mil for the stream. Highway robbery at its finest. But it’s ok, because we share in the loot by investing in the Golden Portfolio.
Creating Value From A Spinout
Hemlo Mining bought the Hemlo mine from Barrick for $1.09 billion in November.
The prolific Hemlo camp has produced over 25 million ounces of gold since the 1980s.
In 2024, tired Hemlo produced only 39K gold ounces at $1,689/oz AISC generating just $37 mil FCF at average $2,387/oz gold price representing only 2% of Barrick’s total FCF.
Like most majors, Barrick has been consolidating operations over the past few years focusing on the largest most profitable mines, and selling smaller non-core assets.
Focused Hemlo Mining should be able to breathe some life back into the asset.
They released a feasibility study on Hemlo in October that shows average 154K gold ounce production over a 14-year mine life.
The study was done using average $2,780/oz gold beginning with $3,195/oz in year 1 dropping to $2,610/oz in year 2038. At current $4,300/oz gold price Hemlo mine shows a NAV of $2,192 mil.
Wheaton will receive 10.13% of gold production paying 20% of spot until 135,730 ounces are delivered, then 6.75% to 117,998, then 4.5% for the life of mine.
Wheaton will receive a total of 189K gold oz at 80% net (after deducting 20% spot ongoing payment).
At current $4,300/oz gold price 189K gold ounces are worth $649 mil. Wheaton only paid Hemlo 46% of the value based on the current gold price.
Why GP Loves Royalties
If the gold price just maintains current levels, Wheaton banks $349 million, swapping $649 million of its gold that it bought for $300 million at $4,300/oz.
God only knows how high gold will rise over the next 13 years.
It’s highly probable gold in 10 years (or less) will trade with 5 digits with Wheaton banking even more profits.
All the players in the industry look at cash flows on a discounted basis. Using a 5% discount rate per year total $649 million, FCF is worth $488 million NAV.
If we account for the $300 million upfront spend in year one and discount at 5%/year the $649 million FCF is worth $349 million NAV.
The gold price that balances out the cash flows is $2,520/oz. That’s a 41% discount to the current gold price. That’s the effective gold price Wheaton is paying for Hemlo’s gold.
I don’t care if you are buying gold in any form: bars, coins, gold stock ETFs, gold miners, or crypto gold tokens. You will never find a better deal. That’s why I love royalties.
Banker’s Gold Price Deck Estimates Are Wrong
Feasibility studies use Banker’s price deck estimate for the gold price.
In Hemlo’s case the gold price estimate started at $3,195/oz and declined to $2,610/oz in 2030.
On average, the gold price used was $2,780/oz for Hemlo’s feasibility. This feasibility study on Hemlo came out in October 2025. The gold price was $4,300/oz then, basically the same as now.
Listen, you can’t change yesterday and you don’t know what will happen tomorrow. All you really have is today, and today the gold price is $4,300/oz. I don’t know why feasibility studies use a discounted gold price to measure NAV.
It helps being conservative, but wouldn’t it be more logical to shave average grade a bit, or maybe add to costs so they increase year by year instead of a constant USD figure per tonnage basis over a 14 year life of mine?
I’d love to see a study of Banker’s gold price deck estimates over the past few years.
There’s no doubt they have been off by $1,000s of dollars. I don’t understand why the industry looks to banker’s price decks as the “be all and end all” for gold price estimates when they have missed this entire gold bull run.
Just because some arrogant ivory-tower economist predicts gold will be $2,610/oz in 2030 is not our problem. It’s our opportunity. Golden Portfolio knows our trade partners are walking away from U.S. debt, and choosing gold instead. Golden Portfolio knows U.S. President Donald Trump and Treasury Secretary Scott Bessent are going to lower rates aggressively, well below the rate of inflation. Golden Portfolio knows Stephen Miran, author of The Mar-A-Lago Accord, is at the Fed determined to devalue the dollar. Golden Portfolio knows crypto tokens are buying hundreds of tons of gold/year, creating an asset-backed monetary standard as a superior product to the U.S.’s current debt-based system.
The USD is done.
It’s gold time.
God only knows how high gold will climb.
That’s Their Loss And Our Opportunity
I understand bankers base their loans to miners off the feasibility study because it’s looked at as the gold standard for valuation. But the major factor to measure FCF and NAV is the gold price. And the gold price used to measure the lifetime stream of profits is off by $1,690/oz or 39%.
That’s why I measure Royalty and Miner FCF based on the current gold price and latest production and costs. That’s how I was able to predict Newmont was trading at a 40% discount to fair value based on math, data, probability and statistics versus some ivory tower economist’s estimate of the future gold price. Newmont’s now trading at $101 per share and is only back to fair value.
Let me tell you right now, 4Q25 royalty and gold miner earnings are going to absolutely blow away the Street. The average gold price in 4Q25 to date is $4,115/oz vs $3,453/oz in 3Q25. That’s an increase of 19% versus a 5% increase from 2Q25 to 3Q25.
When 4Q25 earnings are reported in early 2026, the Street is going to be amazed by the FCF generation.
Gold miner and royalty profits are determined using a simple average gold price calculation from 9/30/25 to 12/31/25, but the Street still can’t figure it out because they are looking at Banker’s price decks showing a declining gold price.
I don’t understand why miners agree to these onerous stream and debt deals based on life of mine (“LOM”) profits based on a gold price that’s 39% below current. Maybe because they are so desperate. But once again that’s not our problem. That’s our opportunity to load up on the royalty-based Golden Portfolio.
And There’s Even More Upside
Ten years is the standard LOM because who really knows where anything will be in 10 years.
Additionally, due to the time value of money, anything after 10 years is so heavily discounted that additional years don’t add much to the NAV. $1 next year is worth $0.95 at 5% discount rate. $1 in year 11 is worth only $0.58.
Sure, we are talking about a $349 million profit at $4,300/oz gold, but in 10 years Wheaton could bank $455 million profit at $5K gold, and $1,210 million profit at 10K gold.
10 years ago the gold price was at $1,200/oz, and based on continued exorbitant government spending, $37 trillion debt load and Trump’s “growth at all cost” plan, there’s no bottom for the USD and no top for gold.
Sure, there’s risk that a mine will not meet expectations, but probability favors exploration success and life of mine extension.
Once a mine begins production, brownfields exploration begins to find more ore.
Mines more often than not operate for much longer than the original 10-year plan.
All extra ounces of production beyond plan represent additional straight profit and straight up shareholder value creation to the Royalties.
And in my new interview with Porter, I explore these companies and this strategy in far more detail.
As well as detail how I’m preparing for gold’s next leg up… and why I believe investors who own my top gold royalty stocks could potentially see remarkable long-term returns.