Editor’s note: For the month of August, we’re shifting the publication schedule for The Trading Club to bi-weekly updates. We will post our next update on September 4, after which we’ll return to our regular weekly publishing schedule.
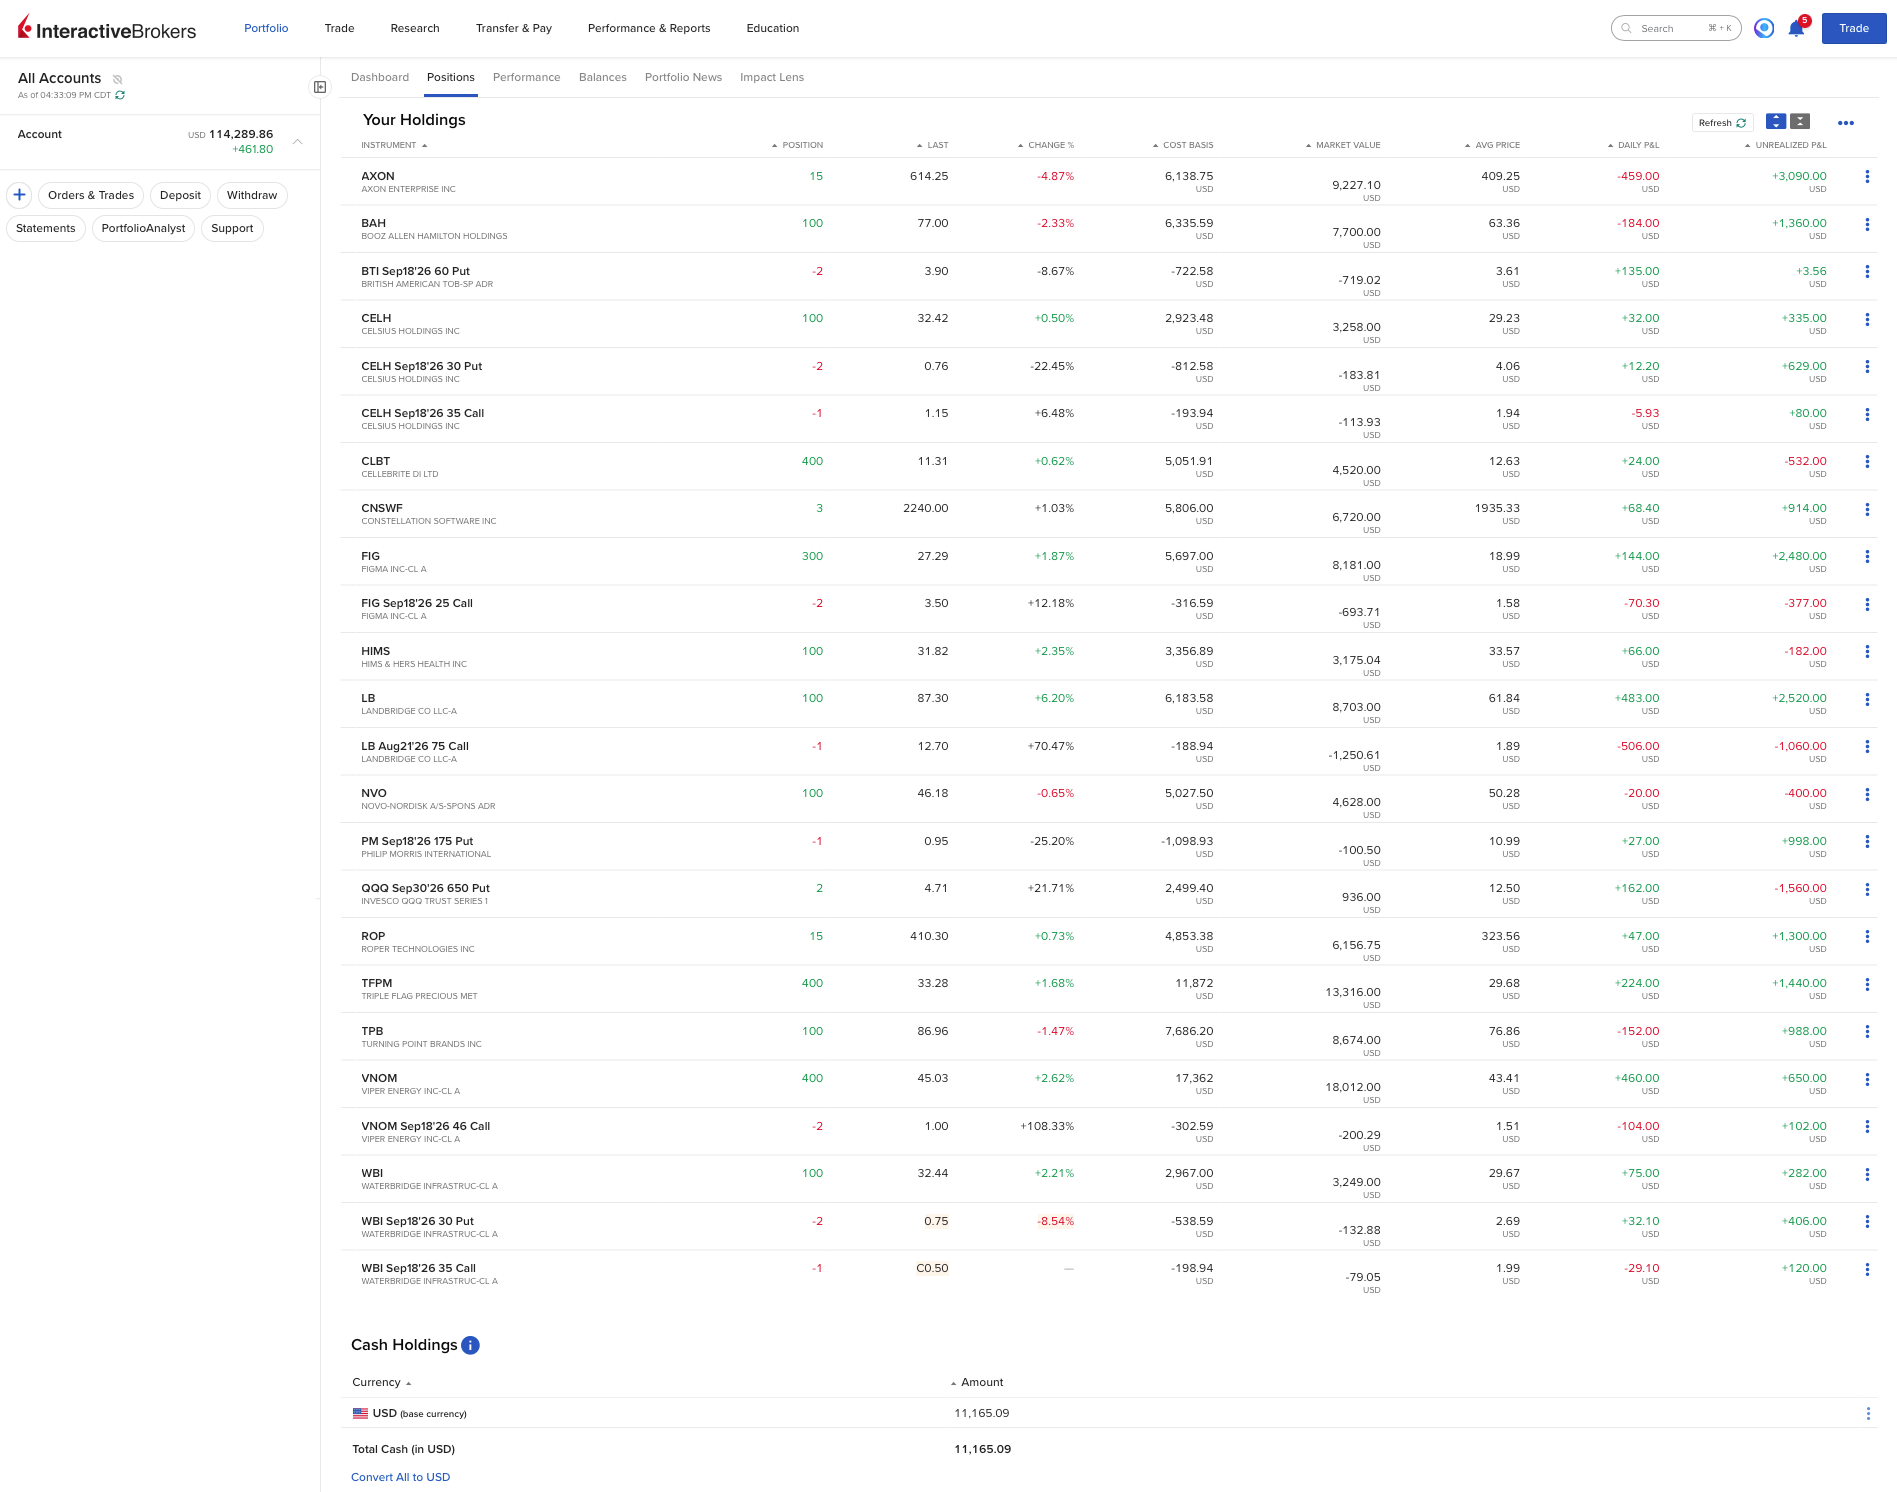
The value of The Trading Club Pro tracking portfolio settled at $114,290 as of Thursday, August 20 – up 14.3% since the June 22, 2026, inception date (see the detailed portfolio snapshot below). We made no trades this week.
In this issue we provide an update on a covered-call position expiring today, review the latest earnings report from one of our software holdings, and address a recent subscriber question in the “Mailbag.”
Update On LandBridge Covered Call Expiring Today
The following covered-call contract on our 100-share position in West Texas land leasing company LandBridge (NYSE: LB) is set to expire at the close of trading today:
One LandBridge (NYSE: LB) $75 covered call, expiring August 21, 2026
No action is needed as we plan to continue holding the position through today’s expiration date.
With shares of LandBridge trading just under $90, the option is likely to expire in-the-money at the close of trading today. In this scenario, our shares will get called away, meaning our broker will automatically sell our 100-share position at the $75 strike price after the close of trading today.
Conversely, if shares fall below the $75 strike price by the close of trading today, the option will expire out-of-the-money and we will retain our 100-share position.
Either scenario is an acceptable outcome for us. Let’s briefly review the latest quarterly results and the valuation of the business that leads us to this conclusion.
LandBridge reported excellent Q2 results on August 5, including revenue of $67 million, up 41% year-on-year (“YOY”), while net income increased 68% YOY to $31 million. The company is benefitting from the resumption of drilling activity across the Permian basin, as the major drillers like ExxonMobil (XOM) and Chevron (CVX) add new drilling rigs in response to higher oil prices. And with oil production on the rise across the Permian, this is leading to greater volumes of produced water, translating into higher royalty payments for LandBridge.
Based on the steady growth in drilling activity, the company reiterated its 2026 outlook for EBITDA (earnings before interest, taxes, depreciation, and amortization) to reach $220 million. It also announced advanced discussions with seven counterparties representing over 10 gigawatts of power and data center capacity for land leasing deals. LandBridge CFO Scott McNeely characterized these as projects with signed documents undergoing diligence or agreements currently under negotiation, rather than preliminary outreach. He also noted that the counterparties include a mix of hyperscalers, engineering, and procurement companies, as well as power generation businesses.
Management expects that “multiple” of these negotiations could convert into firm leases with revenue beginning to flow in by the end of next year, although no formal deals have yet been announced. But that hasn’t stopped the market from beginning to price in this potential future upside, as the shares have enjoyed a significant valuation re-rating in recent weeks.
At just under $90 per share, LandBridge trades with a $7.9 billion enterprise value (“EV”), putting its valuation at a relatively rich 36x EV/EBITDA ratio. That’s a 15% premium to Texas Pacific Land (TPL), currently trading at 31x EV/EBITDA, with both companies growing at similar rates.
While the business is performing well, we are ok with taking profits on the stock. At today’s stretched valuation, we believe investors are paying up for shares based on the promise of future data center deals that have yet to come to fruition. That presents a risk of a valuation de-rating in the event that these deals fail to materialize, or take longer to begin generating revenue than the market is currently pricing in. For now, we’ll continue monitoring the story and may re-enter the position should the opportunity present itself.
In the meantime, we plan on reinvesting a portion of the freed-up cash we expect to receive if the shares close above the covered-call option strike price today.
And for that, we turn to the latest opportunity provided by what we view as an over-reaction to a minor hiccup in the quarterly report from one of our favorite software stocks.
Cellebrite’s Minor Sales Hiccup Creates Buying Opportunity
Digital forensics platform Cellebrite (Nasdaq: CLBT) delivered modestly disappointing Q2 results on August 13. The company generated $131 million in Q2 revenue, or just shy of the $132 million analysts estimated, while earnings per share of $0.11 was in line with expectations. Management also reduced its forecasted revenue for the full year down by 3% to $555 (at the midpoint of the guidance range). However, despite the revenue downgrade, management increased its forecast for adjusted EBITDA up by 3% to $156 million for 2026.
The primary cause of the sales weakness was attributed to a slower pace of deal closing for the company’s cloud-based software offerings, which were stymied by unexpected regulatory steps. This resulted in a slightly elongated sales cycle, although no deals in the company’s sales pipeline were lost, as we’ll discuss in greater detail below.
In isolation, we viewed the revenue weakness in Q2 and downgrade in management’s outlook as modest disappointments. But the company also announced the unexpected retirement of CEO Tom Hogan, to be replaced by the former President of Products and Technology, Shiv Ramji, effective immediately.
While it’s never good to see an earnings miss followed by a guidance cut, it’s even worse when accompanied by a sudden shakeup in leadership. We suspect it was this confluence of negative bits of news that drove the stock down 30% following the report, with some investors likely viewing the sudden CEO change as evidence of deeper problems within the company. However, after looking closely through the numbers and the management commentary from the earnings call, we believe the share price sell off was an extreme over-reaction.
Let’s start by setting the stage for the regulatory obstacles the company is facing. As we’ve written about previously, in order to legally sell cloud-based software to any agency of the U.S. federal government, the vendor must first secure approval from the Federal Risk and Authorization Management Program (“FedRAMP”).
Cellebrite secured FedRAMP approval on May 6, and management expected an immediate boost in sales from a healthy backlog of customer demand for its new cloud-based offerings starting in Q2. However, even after securing this approval, the company faced a new and evolving set of requirements that involved “multiple waivers, security reviews, and other other administrative approvals” in finalizing several of its large-scale cloud deals in Q2. CFO David Barter provided the following commentary on the earnings call that put the scope of these delayed deals into perspective:
When you put the quarter in context, we signed and took down orders probably well north of 1,000. In the end, it kind of came down to four, and it was four that crossed the line, and it was four that involved cloud. One in particular involved a platform. You might recall one of these deals we alluded to last time where they actually called us before we had FedRAMP approval. Even they were a little bit surprised about the changing procurement requirements when you get into cloud and AI and the approvals that we had to secure.
In other words, we’re talking about just four deals that contributed to the unexpected weakness in Q2. And importantly, none of these deals were lost, but merely delayed. Chief Revenue Officer Marcus Jewell noted on the call that $4 million worth of sales that were delayed in Q2 have since been closed as of the day of the conference call.
Now admittedly, a slower pace of deal closings will act as a modest drag on the rate of revenue growth over the next couple of quarters. However, the impact here should also be relatively muted over the long-run, with management estimating that the sales cycle was elongated by approximately six weeks for its cloud-based software sales.
Even with this slower sales cycle, the 3% decline in full year revenue for 2026 is far from a thesis-killer, with the company still on track to increase revenue by 17% this year at the midpoint of its updated guidance.
The bottom line is that we saw nothing in the report or in management commentary that should lead to any meaningful impairment to the long-term outlook for the business. Conversely, we saw signs of ongoing strength in the core business from the improving net revenue retention rate, which increased by two percentage points over Q1 to 117%. This tells us that the retention and expansion within the existing customer base actually improved sequentially, even as the growth rate from new sales slowed down from an elongated sales cycle.
We’ll also point out that there’s a flipside to the stringent regulatory requirements Cellebrite faces in selling cloud-based software to government agencies: it further widens the competitive moat around the business. Cellebrite is the only company among its peers that has achieved FedRAMP approval, which management described as a “long and tortuous process” on the Q2 earnings call. So as difficult as it is for the incumbent (Cellebrite) to navigate this complex regulatory environment, this also creates an incredibly high barrier to entry for smaller rivals that have fewer resources, and less of a track record in working with regulators, to overcome.
Meanwhile, the final thing we’ll point out is that ultimately its earnings and free cash flow (“FCF”) that determine the worth of a business, not the top-line revenue growth rate. And on this last point, we actually saw an improving outlook from the Q2 report, as management upped its earnings outlook by 3% for the full year while reiterating its 30% FCF margin target. This is a result of the company successfully scaling up the business while keeping its costs stable, including headcount – which remained unchanged through Q2 relative to the end of 2025, even as the business grows at mid-teens rates. Looking ahead, management noted that it is “increasingly optimistic about our potential to deliver the next step-up in our profitability and FCF in 2027 as we demonstrate that we can operate the business without material expansion of the headcount.”
Putting it all together, we see a business on track to increase revenue at a healthy mid-teens annual rate while generating approximately $167 million in FCF this year. At a recent price of around $11, the business trades at a market capitalization of $2.8 billion, with a pristine balance sheet that contains just over $500 million in net cash. That translates into an EV of $2.3 billion, and a valuation ratio of just under 14x EV-to-FCF compared with over 33x for the S&P 500.
Given Cellebrite’s dominant competitive position, wide structural moat, and high cash flow margins, we see no reason why this business should trade at a market discount. We suspect investors have grown frustrated with the shares after a year and a half of setbacks, starting with DOGE-related fears in early 2025, the perceived AI threat to all things software earlier this year, and now a guidance cut and CEO reshuffling. But simply looking at the objective business fundamentals, we see a deeply discounted stock where the underlying customer base remains sticky and a solid growth outlook.
Assuming the worst is behind it and the company achieves the latest guidance set out by management, we see no reason why the shares won’t compound in line with revenue growth going forward, at a high-teens rate. Plus, we also see significant upside potential from the valuation re-rating higher towards a market multiple, which would more than double the share price alone.
Our plan is to take advantage of this opportunity to increase our position in Cellebrite, using a portion of the freed-up cash from the LandBridge option expiration, assuming the option expires in-the-money at the close of trading today. That cash will be available for investment on Monday morning, at which point we’ll issue a new trade alert.
Next, we’ll show each position in the portfolio broken down by trade type.
Portfolio Review
The table below shows all current holdings as of the close of trading on Thursday, August 20:
A few notes on how to read and interpret this portfolio table.
Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.
Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:
Position size = number of contracts x 100 x put strike price
We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.
For example, in the case of the WaterBridge Infrastructure (NYSE: WBI) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade. It’s commonly referred to as the “notional value” of the trade.
To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.
We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:
- On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
- On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here
As a reminder, we calculate the leverage ratio using the following formula:
Leverage ratio = total long exposure/portfolio equity value
We define total long exposure as the sum of all long positions, including uncovered stocks, covered stocks, cash-secured puts, and option purchases. In the current portfolio, as of Wednesday’s close, these values were as follows (note: we show each value in our portfolio table below):
- Uncovered stocks: $75,855
- Covered stocks: $27,345 (netting out the underlying stock value against the covered-call value)
- Put sales: $41,500 (this “notional value” is the value of stock we’ve committed to purchasing)
- Long options positions: $942
Adding up all of these values gives us $145,642 of total long exposure in our current tracking portfolio. We then divide this number into our account equity of $114,290 to arrive at a 127% leverage ratio – well within our self-prescribed limit of 150%.
Next, we address a recent question from the “Mailbag”
Mailbag
Please note that nothing we write should ever be considered individual investment advice, as we are not licensed to provide such guidance. This material is for educational purposes only, and we recommend consulting with a licensed financial advisor for individual investment advice.
Today’s “Mailbag” letter comes from a subscriber with a question about our position in Celsius in the context of the recent sell recommendation of the stock in the Porter & Co. flagship advisory, Complete Investor.
I received the alert to sell Celsius Holdings (CELH) in Complete Investor, but there was no recommendation for the holdings in The Trading Club. Is Celsius still a recommended hold in The Trading Club, and if not, is the recommendation to close the options positions?
Ross Comment: Yes, we continue recommending holding the existing positions in Celsius Holdings (Nasdaq: CELH) in The Trading Club for the reasons described in our prior update on August 7.
With different analysts running the different publications at Porter & Co, we will sometimes have differing opinions on the same stocks. Plus, the option trading strategies in The Trading Club means we will sometimes have slightly different objectives versus a publication like Complete Investor that’s catered toward a buy-and-hold strategy.
For now, we’re happy to stick with our current strategy of selling options on Celsius, as we believe the downside risk is limited at current prices, while the elevated option premiums offer an attractive source of steady income potential.
If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.
Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.
Good investing,
Ross Hendricks
Porter & Co.